
Finding a mortgage broker for first timers shapes how confidently you approach your first home purchase in 2026. You can obtain pre-approval more quickly without direct broker service fees by partnering with a licensed Australian mortgage broker who connects you to dozens of competing lenders. Local guidance simplifies the home buying journey while reducing paperwork stress, so you can weigh deposit size, income type and lender fit before you sign anything.
Key Takeaways: A mortgage broker simplifies your first purchase by comparing over 60 lenders and managing the entire application to settlement process at no direct cost.
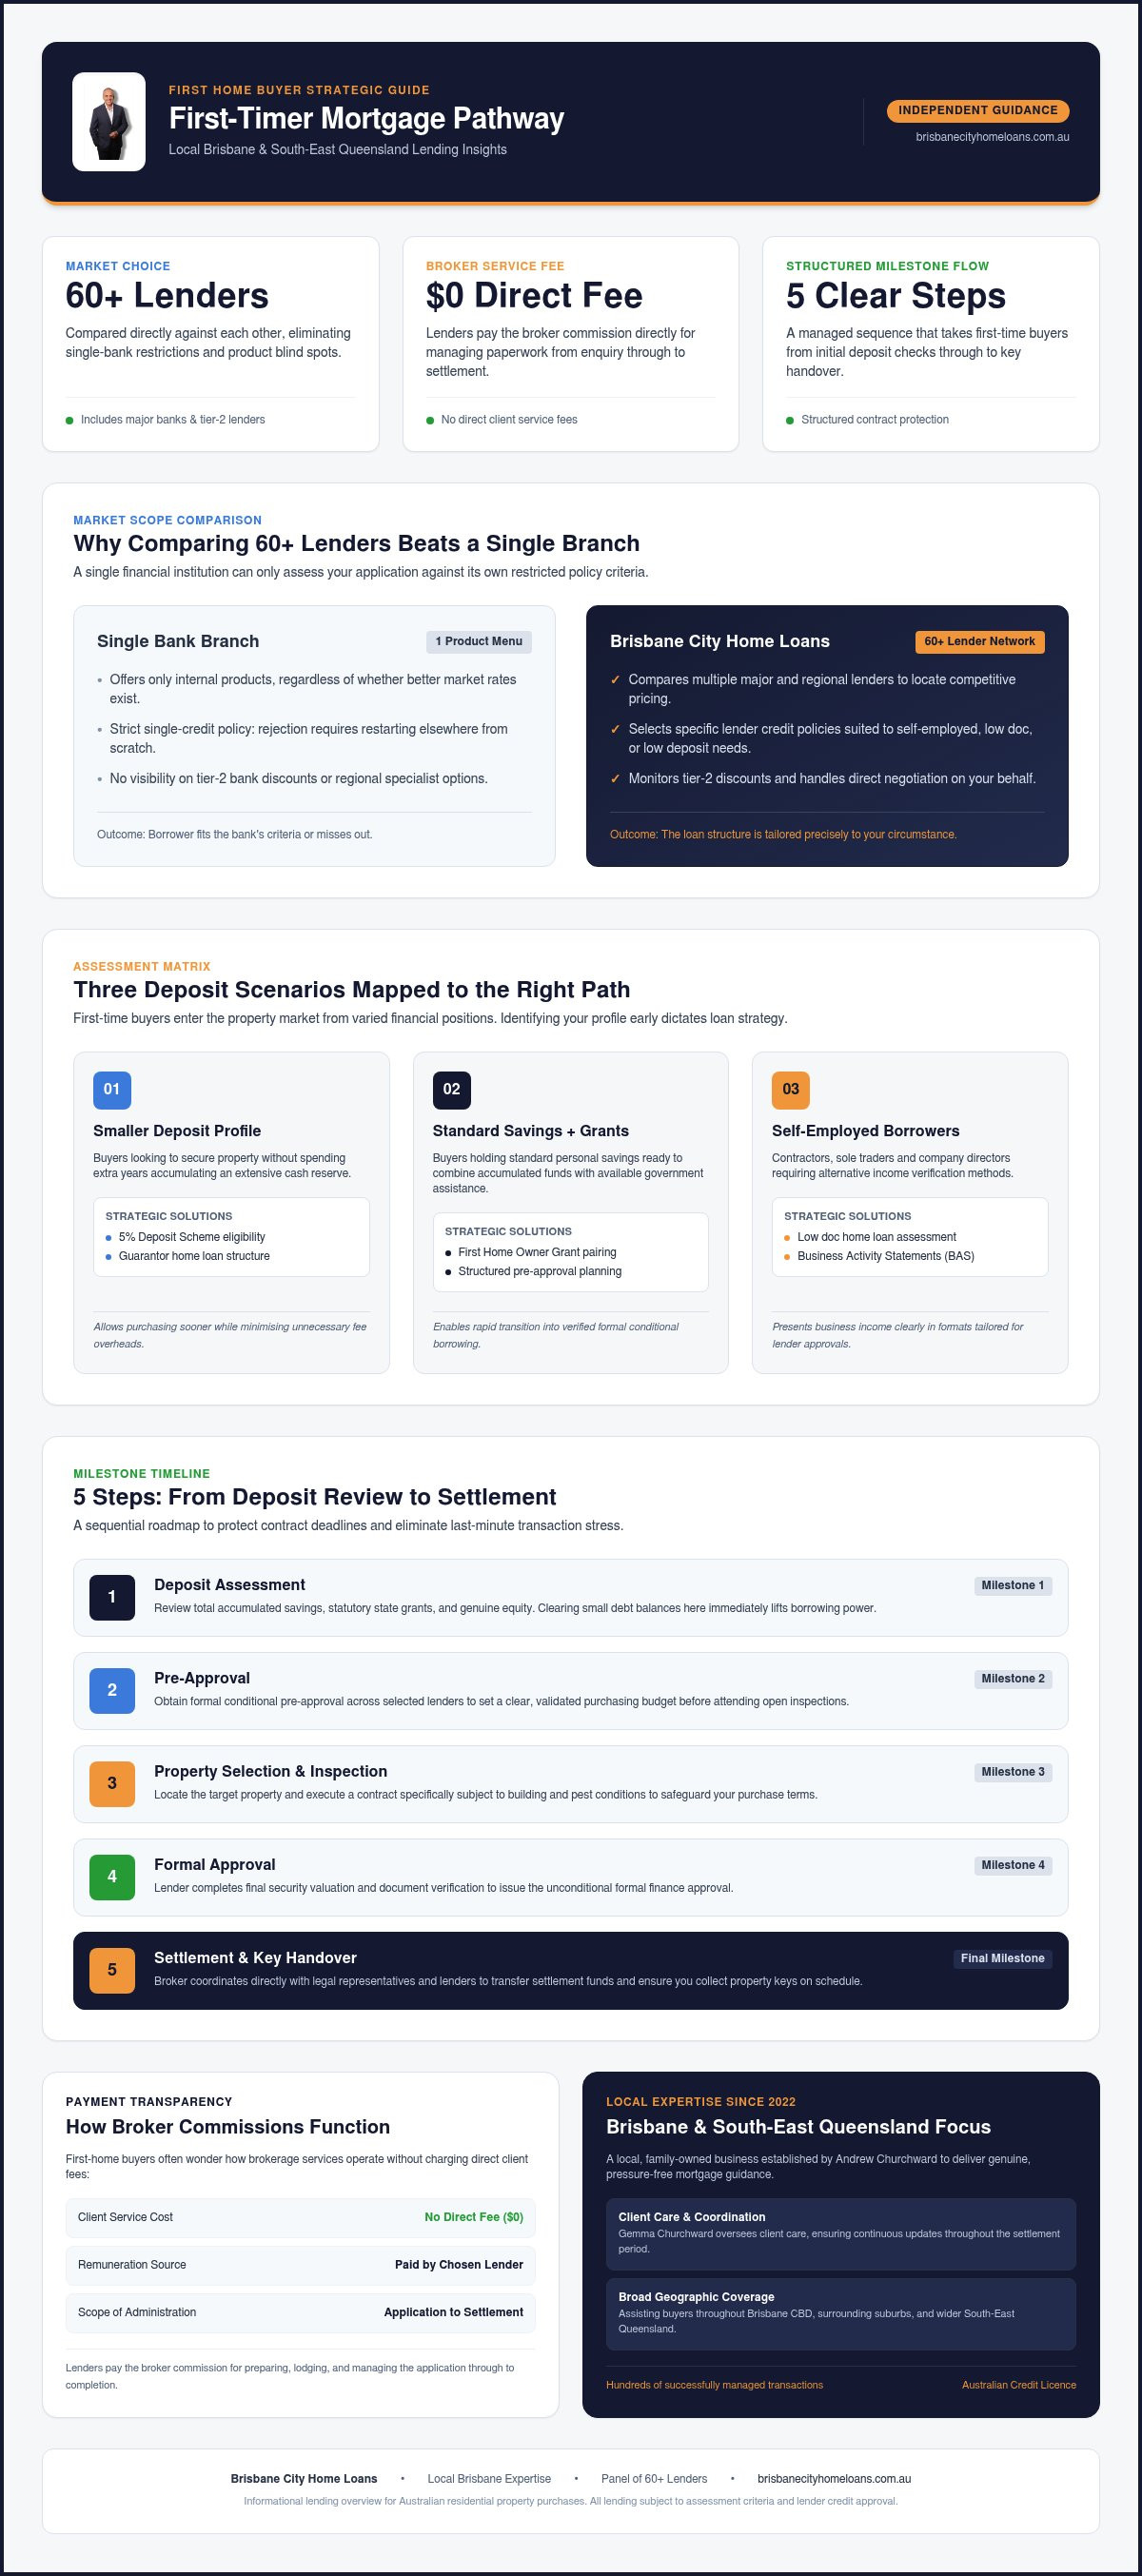
- Access 60+ different lenders to find competitive rates and flexible policies that a single bank branch cannot offer.
- Follow a 5-step timeline from deposit assessment and pre-approval through to formal approval and final settlement.
- Prepare specific documents like Business Activity Statements if self-employed or verify 5% deposit scheme eligibility.
- Pay no direct service fees because lenders pay the broker commission for managing your paperwork.
A mortgage broker for first timers maps three deposit scenarios to the right path
Your deposit size and income type determine which lending path fits your situation. First-home buyers often feel hesitant, doubtful and unsure where to start. Working through real scenarios removes that uncertainty early.
Here is a short guide to three situations we see often, each with a concrete next step drawn from the options already available to you:
- Smaller deposit: you might qualify for the 5% Deposit Scheme or use a guarantor home loan to avoid extra fees, so you can buy sooner without waiting years to save a larger sum.
- Standard savings with state support: buyers who already hold typical savings can pair those funds with support such as the First Home Owner Grant and move straight into pre-approval planning.
- Self-employed income: alternative paperwork, such as a low doc home loan supported by a Business Activity Statement (BAS), lets you present income in a form lenders will assess.
National lending data continues to track these shifting entry points for new buyers. Choosing the right structure saves time and stress. A local team at Brisbane City Home Loans compares 60+ lenders to match your exact profile, so you gain clear guidance without corporate pressure. More on this: Brisbane City Home Loans.
Writing in the northbrisbanehomeloans.com.au thread "Top Mortgage Brokers Brisbane Reviews", one user noted:
"Being first home buyers we went into this with no experience. We had heard that the team you have can make or break the stress of it all." (source)
Unfamiliar processes create hesitation, but matching your scenario to the right lender structure restores confidence quickly. Personalised support helps you move forward without unnecessary pressure. If you are unsure where you stand, bring every question to a no-obligation chat and get a straight answer on deposits and structure.
How a home loan broker cuts paperwork and lender guesswork
A mortgage broker acts as your independent guide, comparing suitable loan options across multiple lenders to simplify your property purchase.
First-home buyers often feel intimidated by complex banking paperwork and confusing finance steps. According to the Wikipedia article on mortgage brokers (2026), a broker serves as an intermediary who negotiates loan terms on your behalf. At Brisbane City Home Loans, we recently helped new buyers who felt completely overwhelmed by the application process. Andrew guided them through every milestone clearly, answered their ongoing questions promptly, and kept them informed until settlement. That dedicated personal support turned a stressful property purchase into an easy, confident success.
To find competitive terms and rates suited to your needs, Andrew evaluates more than 60 different lenders. He manages the entire application through to settlement at no direct cost to you, as lenders pay the broker commission. You can also read our upgraders loan strategy guide to see how loan strategy evolves for your next purchase. Working with a local specialist removes the guessing game entirely.
Tip: Engaging a broker who searches over 60 lenders ensures you do not miss tier-2 bank discounts.
A commenter in the northbrisbanehomeloans.com.au thread "Top Mortgage Brokers Brisbane Reviews":
"Matthew and the team at North Brisbane Home Loans turned what felt like a pipe dream of owning our first home into a reality. Matthew was able to demystify the process for us and help us confidently purchase our own home within a very tight time frame!" (source)
That feedback shows how personal guidance turns a complex home buying process into a manageable experience for first-time buyers. Ask for a free, no-obligation conversation when you want straight answers without jargon or homework.
5 Steps that take you from deposit review to settlement on time
Securing a mortgage takes you from initial deposit review through to final property settlement in a clear sequence.
Clearing small debt balances before applying can instantly improve your borrowing power and prevent last-minute stress. The step-by-step path includes:
- Deposit assessment: Review your total savings, statutory grants, and genuine equity.
- Pre-approval: Get formal conditional approval from a lender to set your clear purchase budget.
- Property selection: Find a property and sign a contract subject to building and pest inspections.
- Formal approval: Submit final paperwork to receive your unconditional loan commitment.
- Settlement: Coordinate with solicitors to transfer funds and secure your new home keys.
Managing these milestones carefully protects you against strict contract deadlines. Borrowers face time pressure when trying to secure finance for a property purchase within short contract windows. Working through this sequence systematically removes that strain.
Hadyn O'Connor's purchase shows how the sequence works in practice. The buyers came in as first-home-clients who needed confidence at each decision point; Andrew and the team mapped the five milestones, handled the lender paperwork, and kept contract dates visible the whole way. The outcome was a process that ran smoothly from start to finish, with the buyers feeling confident in every decision. Having clear guidance keeps your contract dates safe. You can skim common broker myths to spot delay risks before they appear.
A dedicated professional who compares 60+ lenders helps you select loan terms tailored to your financial scenario, more like an experienced air traffic controller bringing a loan safely to the runway than a single-product salesperson. Reach out when you want those steps laid out against your own deposit and timeline.
Why comparing 60+ lenders beats a single bank product menu
Direct bank channels limit your choices to one institution, while an independent broker provides access to multiple lending policies across Australia. Walking into a single branch restricts your funding choices significantly. Comparing options across 60+ lenders helps you find a loan structure tailored to your situation rather than adjusting your goals to fit one bank.
Buying a home can feel overwhelming when you face complex product choices alone. You can review calculators versus broker quotes to see how local professional advice differs from digital estimates.
| Feature | Direct Bank Branch | Mortgage Broker |
|---|---|---|
| Loan Choice | Single lender products | Access to 60+ lenders |
| Guidance | Fits you to their policy | Matches policy to your needs |
| Application | You manage the paperwork | Broker handles the process |
Single-bank products suit borrowers with straightforward finances who prefer dealing with their current provider, whereas broad panel comparison fits first-time buyers who need flexible policies or extra guidance. A single lender cannot negotiate against itself to give you wider choices, so panel access is the practical way to test what actually fits.
How broker commissions work so you pay no direct service fee
Most mortgage brokers provide their services at no direct cost to you because the selected bank pays them a commission.
In our local practice, we recently helped a client who worried that extra income beyond base pay would confuse traditional lenders. Andrew understood what mattered to the client, structured a suitable loan and negotiated a competitive interest rate. That clear strategy turned a stressful situation into a successful property purchase, and you save time when an expert handles the paperwork.
A Google reviewer describes Andrew as professional and says they would recommend him. An ASIC 2011 review of mortgage brokers' conduct showed that regulatory oversight helps ensure transparent credit assessments across the industry.
Lender-paid commissions mean you access broad guidance without upfront broker service fees. Direct fees only apply in rare, highly custom arrangements, which we explain fully beforehand. Broker-assisted loans fit buyers who need tailored choices; applying directly suits people with basic income and a single preferred bank. If you worry a broker might cost extra, remember that banks pay the commission directly, so you still receive a no-obligation run-through of your options first.
When staying with your existing bank still makes sense
Walking into your local bank branch can work well if you already hold significant equity or staff discounts there.
From client work, we see how exhausting it feels when a banker dismisses your borrowing ability after a quick assessment. That frustration happens often because individual lenders must stick strictly to their own rigid policy rules.
What few people think of: an existing lender might match a competitor offer if you ask them directly. Sometimes the smartest move is not switching at all, but using a rival quote to negotiate a better rate with your current lender and avoid a loyalty tax on a rate you have outgrown.
Direct negotiation suits borrowers who want a single banking relationship and fit standard lending criteria. Going direct still limits your choices to one product menu. A mortgage broker compares over 60 lenders and gives you an honest recommendation rather than a sales pitch, with personal guidance matched to your real situation across Brisbane and South-East Queensland.
Frequently asked questions
Why should first‑time buyers use a home loan broker?
First-time buyers benefit from expert assistance that streamlines the initial property purchase. Clear guidance tailored to local Brisbane conditions helps you decide on deposit structure, lender fit and timing without guessing.
What does a home loan broker do?
A home loan broker evaluates your financial situation and guides you through the borrowing process. Andrew compares 60+ lenders to secure competitive rates and manages the entire application through settlement for home buyers in the wider region.
How can a broker save me time and money?
Brokers save you time by shopping around across dozens of credit providers on your behalf. According to a Google review, Andrew is described as professional, prompt, and highly recommended for his home loan assistance. This service costs you nothing because the chosen lender pays the broker directly.
What are the steps when working with a broker?
You begin with an initial consultation to discuss your property goals and deposit size. Next, your broker evaluates loan options across a wide panel and submits the paperwork. They then manage the process right up to settlement day.
How can I find a mortgage broker?
Look for local Brisbane specialists with proven customer satisfaction and broad market access. You can read independent online reviews or ask family and friends for direct recommendations. Someone who offers clear communication and straight answers makes the search far simpler.
Next steps for your first Brisbane home
Buying your first property in 2026 feels simpler when you reuse the same decision questions you started with: deposit size, income type, panel comparison versus a single bank, and whether broker-led support or a direct relationship fits you better. Ready to buy your first home? Compare loan options here and get expert, honest guidance. More on this: Mortgage Quote Comparison.
Director and mortgage broker for first timers Andrew Churchward (Credit Representative 379021) compares options across 60+ lenders. Gemma Churchward manages client care, keeping the paperwork moving without pressure. Local buyers praise their professionalism and clear recommendations throughout the lending process. You can ask any question about deposits or loan structures at your own pace. Reach out for a free, no-obligation conversation today to discuss your plans.


