
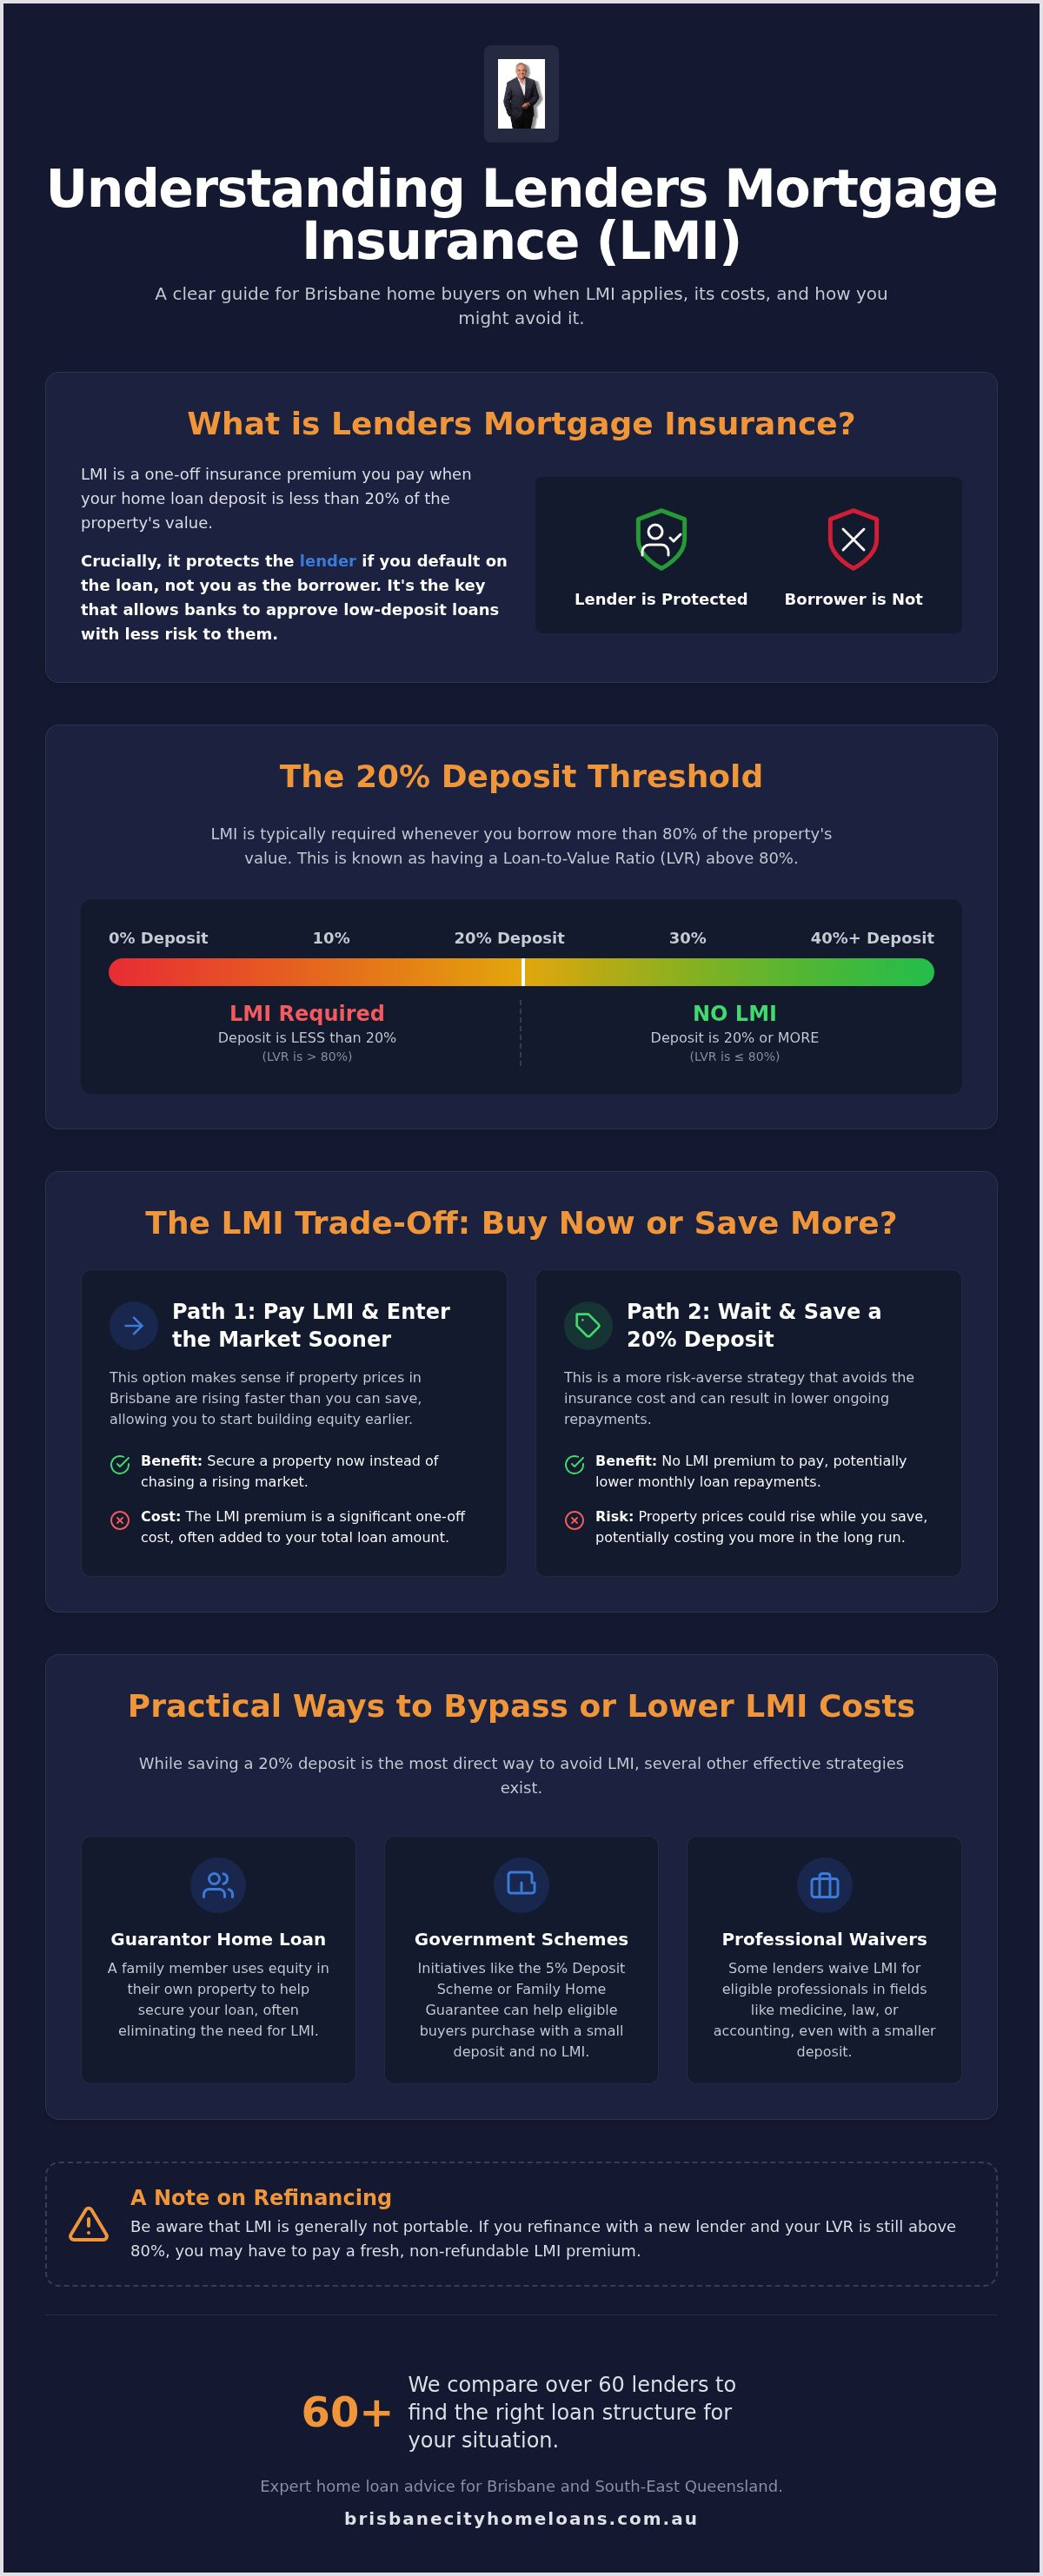
Lenders Mortgage Insurance (LMI) is a one-off insurance premium protecting the credit provider, not you, if you default on a loan with a small deposit (low-deposit loan). This cover applies when your deposit is under 20% of the property value. It allows lenders to approve your home loan sooner while shifting their financial risk to an insurer. Your core decision is simple: pay LMI to buy sooner, or wait and save a full 20% deposit while prices and rents keep moving.
Key Takeaways: Lenders Mortgage Insurance (LMI) is a one-off premium protecting the lender if you default on a home loan with a deposit under 20%.
- Requirement for LMI triggers whenever your deposit is less than 20% of the property value.
- Refinancing with a high loan-to-value ratio often triggers a fresh, non-refundable LMI premium payment.
- Verdict for first-time buyers is to pay LMI if property prices rise faster than savings.
How lmi acts as a fast track or a trap in 3 buyer situations
Fast-tracking your purchase when property prices rise quickly is possible through LMI, though it becomes a trap if repayments stretch your budget. With clients we see that buying earlier with LMI often helps first-time home buyers enter the market sooner. Entering early builds equity (the value of the home minus the debt) faster than saving a larger deposit while prices keep rising across South-East Queensland.
Three situations we see often:
- Strong income, small savings: a low-deposit loan with LMI can secure a home now rather than watching prices run ahead of your deposit.
- Risk-averse budget: waiting to save a full 20% keeps monthly expenses lower and can remove the insurance cost altogether.
- Family support available: a guarantor structure or an eligible government scheme can remove LMI so you keep more cash for costs and buffers.
First-home buyers often feel hesitant and unsure where to start. A local mortgage broker helps you compare over 60 lenders to find the right loan structure without jargon or homework.
Over on the northbrisbanehomeloans.com.au thread "Top Mortgage Brokers Brisbane Reviews", one commenter shared:
"Being first home buyers we went into this with no experience. We had heard that the team you have can make or break the stress of it all." (source)
This experience highlights how overwhelming the property market feels without trusted guidance. Experienced support simplifies complex lending rules and removes unnecessary stress for first-time buyers.
LMI protects the lender, not you, on low-deposit loans
Should you default on your repayments with a small deposit, Lenders Mortgage Insurance protects the bank rather than you.
Entering the property market feels intimidating for first-home buyers facing unfamiliar paperwork and complex terms. LMI acts as a financial safety net for the lender. It enables banks to offer loans even when you have saved less than twenty percent of the property value.
Paying this one-off LMI premium (the insurance cost) reduces the upfront deposit barrier. Think of it like paying for a fast-pass ticket: it lets you enter the market years sooner. Choosing to pay LMI makes sense if property values rise faster than your savings speed.
Fluctuating market conditions directly influence borrowing choices. For more detail on macro trends, read our guide on the RBA cash rate and what it means for your Brisbane property journey. More on this: RBA Cash Rate Explained.
LMI applies when your deposit sits under 20%
Lenders require lenders mortgage insurance when your deposit is under 20% of the property's assessed value. You face a small deposit scenario whenever you borrow more than 80% of the purchase price.
You are rushing to secure a Brisbane property before auction day, but saving that full deposit takes time. Delays risk missing out entirely.
What few people think of: government schemes or family support can remove this insurance cost completely, and some lenders also run professional waiver lists that drop LMI for eligible medical, legal or accounting applicants. Exploring our first-home buyer guide helps you review these pathways quickly.
Saving 20% acts like a sturdy bridge, but a smaller safety margin requires insurer backing. Paying this coverage gets you into the market faster. That trade-off works well for buyers facing rapid price growth. We compare 60+ lenders at Brisbane City Home Loans to find flexible entry options and cut your paperwork stress.
Why the same deposit can attract very different LMI premiums
Lenders calculate your LMI premium using your loan amount, property value, and risk profile. Our client work reveals that for the exact same deposit size, two banks often charge vastly different insurance amounts. This happens because each lender sets its own risk scale and tier structure.
| Pricing Factor | Impact on Cost |
|---|---|
| Loan-to-value ratio | Higher ratios increase the fee |
| Total loan amount | Larger loans raise the risk tier |
Thinking of LMI like a stepped ladder helps make sense of the charges. Stepping just one dollar over a threshold can push you into a higher rate band. Market data places Australian LMI premiums between A$4,000 and A$90,000, with wide variation by deposit size and lender tier. Try our loan calculators to explore your figures and compare options side by side.
4 Steps to calculate and pay your LMI premium
Calculating your LMI premium involves working out your loan-to-value ratio before deciding whether to pay upfront or capitalise it. Arranging finance for a home purchase can feel stressful. We saw this when first-time buyers found the process overwhelming: Andrew explained every step clearly, answered questions promptly, kept updates flowing and guided them through to completion so the journey stayed clear and manageable.
- Calculate your deposit percentage: Determine your saved contribution against the property value to find your loan ratio.
- Estimate the charge: Review lender tables to gauge the LMI premium based on your deposit size.
- Select your payment option: Decide whether to pay the charge upfront or add it to your total balance.
- Finalise with your broker: Confirm the chosen method with your advisor before submitting the formal loan application.
Adding the cost to your loan increases monthly repayments slightly, while paying upfront requires more cash before settlement. Choosing the right approach depends on your savings buffer and monthly budget.
5 Practical ways to bypass or lower LMI costs
You can avoid Lenders Mortgage Insurance by using a guarantor home loan or securing a low-deposit loan (small deposit) through government schemes.
Working with a broker saves time because policy rules vary greatly between banks. Andrew compares more than 60 lenders to secure competitive terms and handles your entire loan process through to settlement at no cost to you.
Some lenders offer professional waivers that completely waive insurance fees for specific medical, legal, or accounting fields. Self-employed borrowers often worry that non-standard income documents will block approval; a skilled broker matches your situation to a lender that accepts that structure.
Tip: Using a guarantor home loan or government scheme like the 5% Deposit Scheme can completely eliminate the need for LMI.
A commenter in the northbrisbanehomeloans.com.au thread "Top Mortgage Brokers Brisbane Reviews":
"He was able to flexibly navigate my unique financial situation and provide solutions. I highly recommend North Brisbane Home Loans" (source)
This review confirms that custom income structures do not prevent you from securing a solid home loan when guided by an experienced local professional.
What refinancing means for an existing LMI policy
LMI is generally non-refundable, so switching lenders often triggers a fresh assessment and, where your new debt still sits above 80% of the property's value, a new premium.
When household changes or family circumstances require rearranging your home loan, you may face that fresh cost if the new loan-to-value ratio stays high. That is why switching makes sense mainly when interest savings outweigh any new policy fees. If you plan to move loans soon, staying with your current lender or negotiating better terms is often the stronger choice for your wallet.
When paying LMI becomes a costly mistake
Paying this fee becomes a mistake if you capitalise it into your loan and refinance shortly after.
From client work we see that moving lenders too soon forfeits the upfront charge while adding new setup fees. Capitalising the cost means you pay interest on that charge for thirty years.
Paying LMI is not automatically the wrong call. Waiting years to save a twenty percent deposit might mean property prices rise faster than your savings. Buying earlier with a small deposit helps you enter the Brisbane market sooner.
Taking a low-deposit loan makes little sense if a family member can provide a guarantor home loan instead. Using equity from a guarantor avoids insurance costs entirely.
Andrew Churchward helps local buyers compare 60+ lenders to check whether paying this cost fits your long-term goals. Request a no-obligation comparison when you want a straight answer on the numbers.
How Andrew Churchward guides Brisbane home buyers
Andrew Churchward compares over 60 lenders to help you secure a suitable home loan without stress. A Google reviewer describes Andrew as professional and says they would recommend him.
Situation: a client came to us to buy their second property and needed clear advice on structure and risk. Solution: we took the time to understand their goals, structured an appropriate loan and negotiated a competitive interest rate. Result: the borrower gained full confidence in their risk profile and moved ahead with a loan that fitted the plan.
Hadyn O'Connor noted that as first-time buyers, the process felt overwhelming at times, but working with Andrew from Brisbane City Home Loans made them feel confident in every decision as the process ran smoothly from start to finish. You get straightforward guidance every step of the way. Book a free chat when you are ready to compare options.
Frequently asked questions
When is LMI required?
Lenders usually require LMI when your deposit is under 20% of the property value. This safeguard protects the bank if you cannot repay your home loan.
If you are buying with a small deposit, this policy applies across most standard Brisbane lending scenarios. Eligible buyers might avoid it using a guarantor home loan or government schemes. Andrew compares over 60 lenders to help you find suitable options for your budget.
How much can LMI cost?
Your cost depends on your deposit size, borrowing amount, and lender guidelines. Across Australian real estate listings, standard industry benchmarks reflect typical figures of A$4,000–A$90,000, with a median around A$14,400.
Larger loan balances automatically increase this overall charge. Every provider calculates this expense using their own internal risk tables. Speaking with a local mortgage broker helps you estimate your specific figure clearly.
How does LMI help me obtain a loan?
It reduces lender risk so banks approve your mortgage with less equity. Buying property sooner becomes possible without waiting years to save a larger sum.
You enter the local housing market much faster. As Google reviewer feedback shows, clients highlight Andrew's promptness and professionalism when explaining these choices. Brisbane City Home Loans provides this comparison service at no cost to you.
How is the LMI premium paid?
Most borrowers capitalise the LMI premium directly into their total loan balance. You pay it off gradually alongside your normal monthly mortgage repayments.
Alternatively, paying this upfront remains an option if you have spare cash ready. Adding it to the principal increases overall interest payments slightly over time. Choosing the right path depends on your current cash position.
What happens if I cannot repay my loan and the home is sold?
The bank sells your property to recover the outstanding balance owed on your mortgage. If that sale fails to cover your full debt, LMI protects the mortgage lender against the financial loss.
This policy does not protect you as the borrower from remaining debts. You remain responsible for any leftover shortfall amount owed to the insurer. Andrew helps you understand serviceability policies (how banks decide if you can afford repayments) so your loan stays manageable.
Navigating Your Next Step
Understanding LMI helps you make a clear choice for your property goals in 2026: pay the premium to buy sooner, or wait for a larger deposit and save on upfront cost. Paying Lender's Mortgage Insurance (a fee that protects the bank) can get you into your property earlier; waiting for 20% can keep repayments leaner if time and rent allow.
Andrew Churchward (Credit Representative 379021) compares loan options across 60+ lenders. Gemma Churchward keeps your client care experience steady throughout the process.
Our team provides tailored mortgage guidance across Brisbane and South-East Queensland. Get in touch for clear advice without sales pressure. More on this: Contact Brisbane City Home Loans.


