
The biggest mistake you can make right now isn't paying a bit too much for a property; it's the preparation you skip before you even step foot in an open home. With Brisbane's median dwelling value now sitting at $1,080,142, the stakes for local buyers have never been higher. Are you worried about missing out on the $30,000 First Home Owner Grant? Or perhaps you're losing sleep over hidden costs? It's incredibly easy to get tripped up by common first home buyer mistakes QLD residents often face, like confusing your borrowing capacity with your actual buying price.
Buying your first home should feel like a massive win, not a constant battle with fine print. It's completely normal to feel a bit anxious about stamp duty or whether you're truly ready to sign. This guide is here to help you sidestep those expensive traps and heartbreaks with a straightforward, local perspective. We'll walk through a clear checklist of what to avoid, how to maximise your grants, and how to keep your path to settlement completely stress-free. Let's get you into your new home without the headache.
Key Takeaways
- Learn why your borrowing capacity isn't the same as your buying price and how to budget for the sneaky hidden costs that pop up after your deposit is paid.
- Discover how to navigate the 2026 grant landscape so you don't miss out on "free" money like the $30,000 First Home Owner Grant.
- Identify and avoid common first home buyer mistakes QLD locals often make, from ignoring flood maps to signing risky unconditional contracts.
- Understand why the Queensland property market requires a unique strategy compared to the southern states to help you bid with total confidence.
- Find out how having a local guide like Andrew can take the administrative heavy lifting off your plate so you can focus on the excitement of the move.
Why Buying Your First Home in Queensland Feels Like a Minefield
Chasing the Great Australian Dream in Queensland feels a bit different these days. It isn't just about finding a nice spot with a Hills Hoist anymore. The "Sunshine State" premium is real. While Sydney and Melbourne have their own established rhythms, the QLD market moves with a specific, fast-paced energy that can catch you off guard. One day you're casually browsing, and the next you're caught in the emotional rollercoaster of a Saturday auction. It's easy to feel overwhelmed by all the noise. One of the most common first home buyer mistakes QLD locals make is assuming their current bank will automatically give them the best deal. "Winging it" might work for a weekend camping trip, but it's often a recipe for disappointment when you're looking for a mortgage. This guide is here to turn those "what if" anxieties into a clear, confident plan of attack.
The Reality of the 2026 QLD Property Market
The landscape has shifted significantly. With Brisbane's median dwelling value hitting $1,080,142 in late 2026, the entry point for first-timers is higher than it's ever been. Local demand in Brisbane and the Gold Coast is being driven by people moving from interstate and a genuine shortage of available homes. You often need to move fast to secure a place, but you can't afford to make "panic" decisions. Buying a home under pressure often leads to overpaying or skipping vital legal checks. This is why having a local expert in your corner is your secret weapon. You need someone who understands the local streets and the specific pressures of the Queensland market to help you stay grounded.
The "Friendly Local Guide" Approach
This is exactly why Andrew started Brisbane City Home Loans. His approach is built on a simple idea: no jargon, no judgment, and no stuffy suits. We want to make this process feel human again. Instead of you trying to navigate 60+ lenders on your own, Andrew does the heavy lifting for you. We break down the complex options into a few clear choices that actually make sense for your budget. When you first reach out for a chat, it's low-pressure and entirely about you. We'll talk through your goals and look at the numbers together. Our job is to handle the paperwork and the bank back-and-forth. We want you to avoid common first home buyer mistakes QLD and focus on the fun part; finding the right keys for your front door.
The Financial Fumbles: Borrowing Power vs. Buying Power
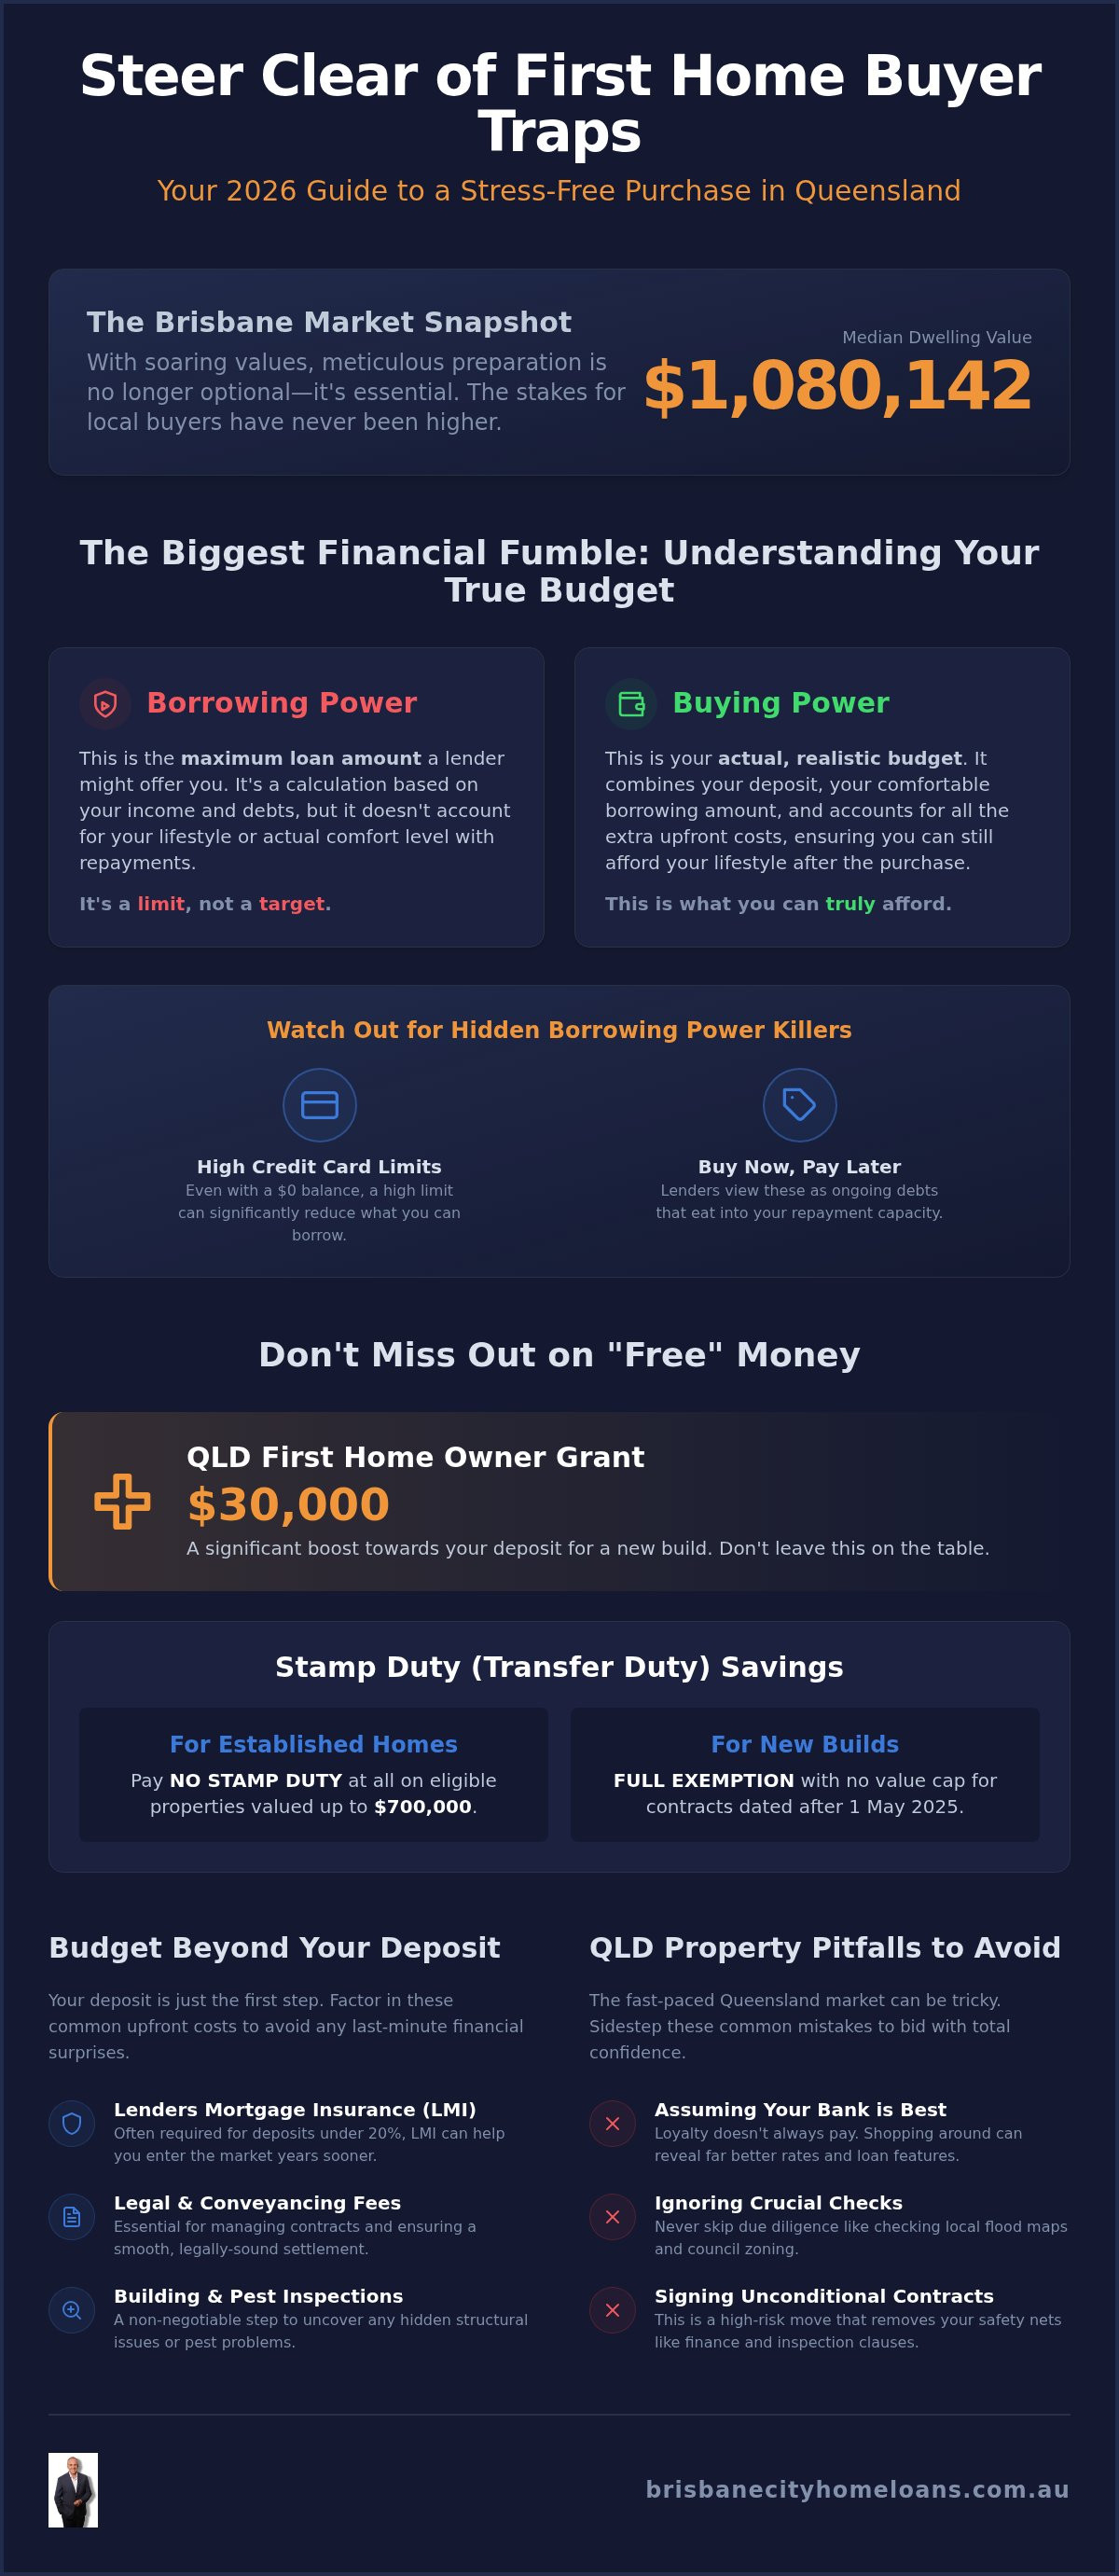
One of the most common first home buyer mistakes QLD residents stumble over is looking at a bank's maximum loan amount as a target rather than a limit. Just because a lender says they'll give you $900,000 doesn't mean your lifestyle can handle those repayments. You still want to be able to afford a coffee at South Bank or a weekend at the coast, right? It's about finding that sweet spot between what you can borrow and what you actually want to spend. Your buying power is your total budget, while your borrowing power is just one piece of that puzzle.
You also need to look beyond the deposit. Even if you've saved a 5% deposit, you'll need a bit of extra cash tucked away for "hidden" costs. We often see buyers forget about Lenders Mortgage Insurance (LMI). While some see LMI as a waste of money, it's often a ladder that helps you get into the market years earlier. Instead of waiting a decade to save 20%, you pay a premium to buy now. Small things can trip you up too. A $10,000 credit card limit can slash your borrowing power by tens of thousands of dollars, even if the balance is zero. The same goes for "Buy Now Pay Later" accounts; they might seem harmless, but banks view them as ongoing debts that eat into your ability to repay a loan.
Calculating the True Cost of Your First Home
Queensland is actually quite generous with transfer duty (what most people call stamp duty) exemptions. For established homes valued up to $700,000, eligible first home buyers pay no transfer duty at all. If you're looking at a new build, there is currently a full exemption with no value cap for contracts dated after May 1, 2025. Still, you need a buffer for building and pest inspections and legal fees. It's worth checking this Queensland Government advice to see exactly where you stand with these costs. If you are wondering how much deposit for a Brisbane home you really need, remember to factor in these extras so you aren't caught short at the finish line.
The Pre-Approval Power Play
Think of pre-approval as your "fair dinkum" confidence booster. Walking into an open home without it is like heading to the checkout with a full trolley before checking your bank balance. A "conditional approval" basically means the bank likes you, but they need to see the specific house before they say a final yes. It tells the real estate agent you are a serious buyer, not just a window shopper. If you want to get your numbers sorted without the stress, chatting with a local broker is a great way to see where you stand before you start falling in love with properties.
Missing Out on "Free" Money: QLD Grants and Government Schemes
It feels like a massive win when the government offers to chip in for your first home. However; assuming you're automatically eligible for every handout is one of the most common first home buyer mistakes QLD locals make. The rules are strict, and missing a single deadline or criteria can cost you thousands. For instance, the $30,000 First Home Owner Grant (FHOG) is a fantastic boost for those building or buying a brand-new home, but it doesn't apply if you're eyeing off a charming old Queenslander in the suburbs. If you're looking at established properties, your "free money" comes in the form of tax savings rather than a cash splash.
The good news is that you can often stack these benefits to get ahead. You might use the First Home Guarantee to secure a property with just a 5% deposit and no Lenders Mortgage Insurance, while also claiming your grant or duty concessions. It's about knowing which levers to pull at the right time. For a broader look at how these financial pieces fit together, Moneysmart's guide to buying a house is a great place to start your research. Just remember that these schemes often have limited places or specific price caps that vary depending on where in Queensland you're looking to buy.
The QLD First Home Owners Grant Checklist
To grab that $30,000 grant in 2026, your new home must be valued under $750,000. This includes the land and the build cost. You also need to follow the "Primary Place of Residence" rule; you must move in within a year of settlement and stay there for at least twelve months. Many people get caught out by trying to rent the spare room out on day one or moving out too early. Paperwork is another hurdle. A simple typo or a missing bank statement can delay your payment at settlement, which is why having a broker to double-check your application is so vital.
Stamp Duty Concessions in QLD
If you're building on a fresh block, the First Home Vacant Land Concession can save you a significant amount on the land transfer. For those buying an existing home, you currently pay zero transfer duty on properties valued up to $700,000. There's a sliding scale for homes between $700,001 and $799,999, so you still get a partial win. If your deposit is still looking a bit slim even with these concessions, you might want to read our Guarantor Home Loan Brisbane: Your 2026 Guide to Buying Sooner. It's another way to bypass the years of saving and get into your own place much faster.
The Property Pitfalls: Why Location and Legal Ticks Matter
It's incredibly easy to get swept up in the excitement of an open home. You see a sleek renovated kitchen or a stunning outdoor area and start imagining your first Sunday barbie. However, falling for the aesthetics while ignoring the actual "bones" of the property is high on the list of common first home buyer mistakes QLD locals make. This leads us to Mistake #3: Falling in love with the kitchen and ignoring the flood map. You need to look far beyond the fresh coat of paint. For instance, skipping a building and pest inspection to save a few hundred dollars is a gamble you don't want to take. It could leave you with a $50,000 bill for termite damage or structural issues that weren't visible to the naked eye.
Pressure is another factor. In a competitive market, you might feel pushed to make an "unconditional" offer to stand out. For a first-time buyer, this is often the biggest risk you can take. It means you're legally committed to the purchase even if your bank suddenly changes its mind about your finance or the building report comes back as a nightmare. You also need to keep an eye out for zoning and easements. If there's a council sewerage pipe running right where you planned to build a backyard deck, your renovation dreams could be over before they've even started.
Brisbane-Specific Risks: Floods and Overlands
Brisbane has a unique relationship with water, and it's something every buyer needs to respect. Before you get too attached to a street, check the Brisbane City Council flood maps. It isn't just about the big river events; overland flow from heavy tropical storms can be just as problematic. A property's flood history doesn't just affect your peace of mind; it directly impacts your wallet. High-risk zones lead to much higher insurance premiums, and some lenders might outright refuse to approve a loan for a property they deem too risky. The bank needs to know their investment is safe, even if you're already in love with the garden.
The Contract of Sale: Don’t Sign Yet!
Never feel pressured to sign a contract on the spot. Your solicitor should always review the document before you put pen to paper. They'll make sure your safety nets are in place, specifically the "Subject to Finance" and "Subject to Building and Pest" clauses. While Queensland does have a five-day cooling-off period, it isn't a perfect safety net and usually involves a small financial penalty if you pull out. If you want to ensure your finance clause is backed by a lender that actually understands the local market, chat with a local mortgage expert who can guide you through the paperwork.
Getting Your Ducks in a Row: The Stress-Free Path to Settlement
You've found the place. You've checked the flood maps. Now comes the part that often feels like a second full-time job: the paperwork. One of the final common first home buyer mistakes QLD residents make is trying to handle the entire settlement process alone. While it's tempting to think you can DIY your way through the banking bureaucracy, the reality is that one missed signature or a delayed document can put your whole purchase at risk. This is where the administrative heavy lifting happens. Having someone to manage the back-and-forth with the bank means you can focus on more important things; like deciding which wall needs a fresh coat of paint or where the sofa is going to go.
The journey from "Offer Accepted" to "Keys in Hand" usually takes about 30 to 60 days. Once your offer is in, you'll work through your finance approval and building and pest inspections. Andrew stays in your corner throughout this entire window. He organises the documents and keeps the lenders on track so you aren't left wondering what's happening. Even after settlement, the relationship doesn't just end. Many banks hope you'll just "set and forget" your loan so they can slowly hike your rate over time. We call this the loyalty tax. We stay in touch to make sure your loan stays competitive years after you've moved in.
The Brisbane City Home Loans Advantage
Why spend your weekends trying to decipher the fine print of every bank in Australia? We compare over 60 different lenders for you while you get on with your life. There is no direct cost to you for this service; the banks pay us to do the work of finding and setting up your loan. Best of all, you aren't dealing with a faceless call centre or an automated bot. You get personalised guidance from Andrew, a local Brisbane human who actually answers his phone and knows the difference between Chermside and Chandler. It's professional expertise with a humble, local attitude that prioritises your comfort over industry prestige.
Your Next Steps
Ready to see what's possible? Getting started is easier than you might think. You don't need a perfect credit score or a mountain of gold to have a chat. Just gather your recent payslips and bank statements so we can get an initial look at your numbers. We can then book a no-obligation chat to see where you stand and which grants you might be able to grab. If you're considering building your own place instead of buying an existing one, take a look at our guide on Construction Loan Brisbane: Your 2026 Guide to Building Without the Stress. Let's get your plan of attack sorted together.
Your Keys are Closer Than You Think
Buying your first home in Queensland doesn't have to feel like a second job. We've covered a lot today; from the trap of confusing borrowing power with actual buying power to the vital importance of checking those Brisbane flood maps before you sign. By keeping a sharp eye out for these common first home buyer mistakes QLD locals often face, you're already miles ahead of the competition. You've got the knowledge to avoid the expensive heartbreaks and the confidence to ask the right questions.
Now, it's time to put that plan into action. You don't have to navigate the paperwork or the 60+ different lenders on your own. Andrew is here to provide local Brisbane expert guidance and handle the administrative heavy lifting while you focus on the move. Best of all, this service is 100% free for borrowers. Ready to avoid the traps? Book a free, no-obligation chat with Andrew today. You've got this, and we're here to make sure your journey to settlement is as smooth as possible.
Frequently Asked Questions
Can I use the QLD First Home Owners Grant as my deposit?
Generally, you can't use the grant for your initial deposit. Most lenders want to see "genuine savings" first, and the $30,000 grant is usually only paid out at settlement or when the first slab is poured. It's one of the common first home buyer mistakes QLD residents make to assume this cash is available the moment they sign a contract. You'll still need your own savings for that first 5% or 10% payment.
What happens if my home loan application is rejected?
Don't panic; a rejection isn't the end of the road. It often just means your specific situation didn't fit that particular lender's current rules. We can sit down and look at why it happened, whether it was a credit card limit or a specific property type. From there, we compare over 60 other lenders to find a better match. Sometimes a small tweak to your finances is all you need to get a "yes" elsewhere.
How much is stamp duty for a first home buyer in QLD in 2026?
In 2026, you pay zero transfer duty on established homes valued up to $700,000. For homes between $700,001 and $799,999, you'll get a partial concession on a sliding scale. If you're buying a brand-new home, there's a full exemption with no value cap for contracts dated on or after May 1, 2025. These savings make a massive difference to your overall buying power in the competitive Brisbane market.
Is it better to buy an established home or build my first home?
It depends on your priorities. Building allows you to access the $30,000 First Home Owner Grant and design a climate-smart home from scratch. However, established homes in Brisbane suburbs often offer better locations and larger blocks of land. You also avoid the potential stress of construction delays. We can help you crunch the numbers for both paths so you can decide which one feels right for your lifestyle and long-term goals.
Can I buy my first home with a 5% deposit in Brisbane?
Yes, you certainly can. Programs like the First Home Guarantee allow eligible buyers to get into the market with just a 5% deposit without paying Lenders Mortgage Insurance. With Brisbane's median dwelling value over $1,000,000, this makes a huge difference to how quickly you can stop renting. You'll still need a small buffer for legal fees and inspections, but a 5% deposit is a very realistic starting point for many local buyers.
What is the First Home Guarantee and how do I apply?
This is a federal government scheme that acts as a "guarantor" for your loan. It lets you buy with a 5% deposit while the government covers the risk that Lenders Mortgage Insurance usually handles. To apply, you need to go through a participating lender or a broker. As of late 2025, property price caps in Brisbane for this scheme are $1,000,000. It's a great way to avoid common first home buyer mistakes QLD buyers make when over-saving.
Do I need a solicitor or a conveyancer when buying in QLD?
Yes, you absolutely need one or the other. A solicitor or conveyancer handles the legal transfer of the property into your name. In Queensland, we highly recommend having your legal rep review the contract before you sign anything. They check for easements, title issues, and ensure your "Subject to Finance" clauses are worded correctly. It's a non-negotiable step to protect your deposit and ensure the property is legally sound before you take the keys.
How long does the home loan process usually take from start to finish?
You should usually allow 30 to 60 days from the moment your offer is accepted to the day you move in. The initial pre-approval can take a few days to a couple of weeks, depending on the lender's current backlog. Once you've found a place, the formal approval and legal checks take up the rest of the time. Andrew manages this entire timeline for you to ensure everything stays on track for a stress-free move.


