
What if that dated kitchen or the deck that's seen better days wasn't a $50,000 headache, but a hidden treasure chest waiting to be unlocked? You've likely noticed that the cost of living in Brisbane isn't getting any lower. The thought of a massive bank application for a home makeover probably feels like a second job you didn't ask for. It's completely normal to feel stuck between wanting a nicer home and fearing you'll over-capitalise. If you're looking to refinance for renovations Brisbane families are finding that their property's equity is the key to finally getting those tradies through the door without the usual financial stress.
I'm here to show you how to turn your home's value into the lifestyle you've been dreaming of while actually aiming for a lower interest rate. You'll discover how to navigate the 2026 market, including those new Brisbane City Council zoning changes that might just boost your home's potential. I'll walk you through a simple, guided process that doesn't cost you a cent in broker fees. From understanding your exact borrowing power to picking the right lender from over 60 options, we'll make the path to your dream reno feel clear and manageable.
Key Takeaways
- Use the recent growth in Brisbane property prices to unlock the cash you need for that dream kitchen or deck.
- Learn the simple 80% Rule so you know exactly how much equity you can safely tap into without overstretching.
- Find out how to refinance for renovations Brisbane locals use to get a better deal than their current bank is offering.
- Get a clear, step-by-step roadmap for valuations and builder quotes to keep your project moving without the paperwork headache.
- Compare over 60 lenders for free with a local expert who does all the heavy lifting for you.
Why Refinance for Renovations in Brisbane Right Now?
Brisbane is having a proper moment. If you have lived in your home for more than a few years, you are likely sitting on a bit of a goldmine. With the property market showing steady growth into 2026, your home's value has probably climbed higher than you think. This is where Understanding home equity becomes your secret weapon. It is simply the difference between what your house is worth today and what you still owe the bank. As that gap grows, so does your ability to fund a major lifestyle upgrade.
Why consider a refinance for renovations Brisbane wide right now? Moving house is a massive headache. Between real estate fees, marketing costs, and the dreaded stamp duty, you could easily blow $60,000 before you even get the keys to a new place. Why not put that money into your own backyard instead? Whether you are lifting a classic Queenslander to catch the breeze or modernising a 70s brick home in the suburbs, renovating lets you keep the neighbours you like while getting the kitchen you deserve.
Capitalising on Brisbane’s Property Growth
Local demand in Brisbane suburbs is staying strong, and new zoning changes coming into effect on September 18, 2026, are making certain blocks even more valuable. This growth means you have more "usable equity" to play with. Many homeowners fall into the trap of the "Loyalty Tax." This happens when your current bank keeps you on a higher interest rate while offering shiny new deals to people who have just walked off the street. Switching lenders can often unlock a lower rate and the cash you need for that new ensuite or deck. Even with inflation sitting around 3.5%, the value of a well-renovated home in a prime Brisbane pocket continues to outpace the cost of the loan.
Refinancing as a Strategic Financial Move
Refinancing isn't just about getting a hammer and nails. It is about looking at your whole financial picture. With the RBA cash rate sitting at 4.35% and economists like those at NAB predicting a move to 4.60% in late 2026, getting your loan structure right is vital. Your current bank might tell you a "top-up" is the easiest way, but that often locks you into their standard rates. By looking at a full refinance for renovations Brisbane families can often find lenders who are hungry for business and willing to offer much sharper rates to win you over.
- Debt Consolidation: You can often roll smaller, high-interest debts into your home loan to keep monthly repayments manageable.
- Better Features: Some lenders offer better offset accounts specifically for people doing major works.
- Expert Help: When a big bank says "no" because your paperwork looks a bit messy, Andrew can help. Comparing 60+ lenders means finding the one that actually wants your business.
Understanding Equity: How Much Can You Actually Borrow?
Home equity is the difference between your property’s market value and your remaining loan balance. Think of it like a digital piggy bank that grows as your house value goes up and your mortgage debt goes down. If you want to refinance for renovations Brisbane property owners need to understand their "usable equity" before they start picking out tiles or paint colours.
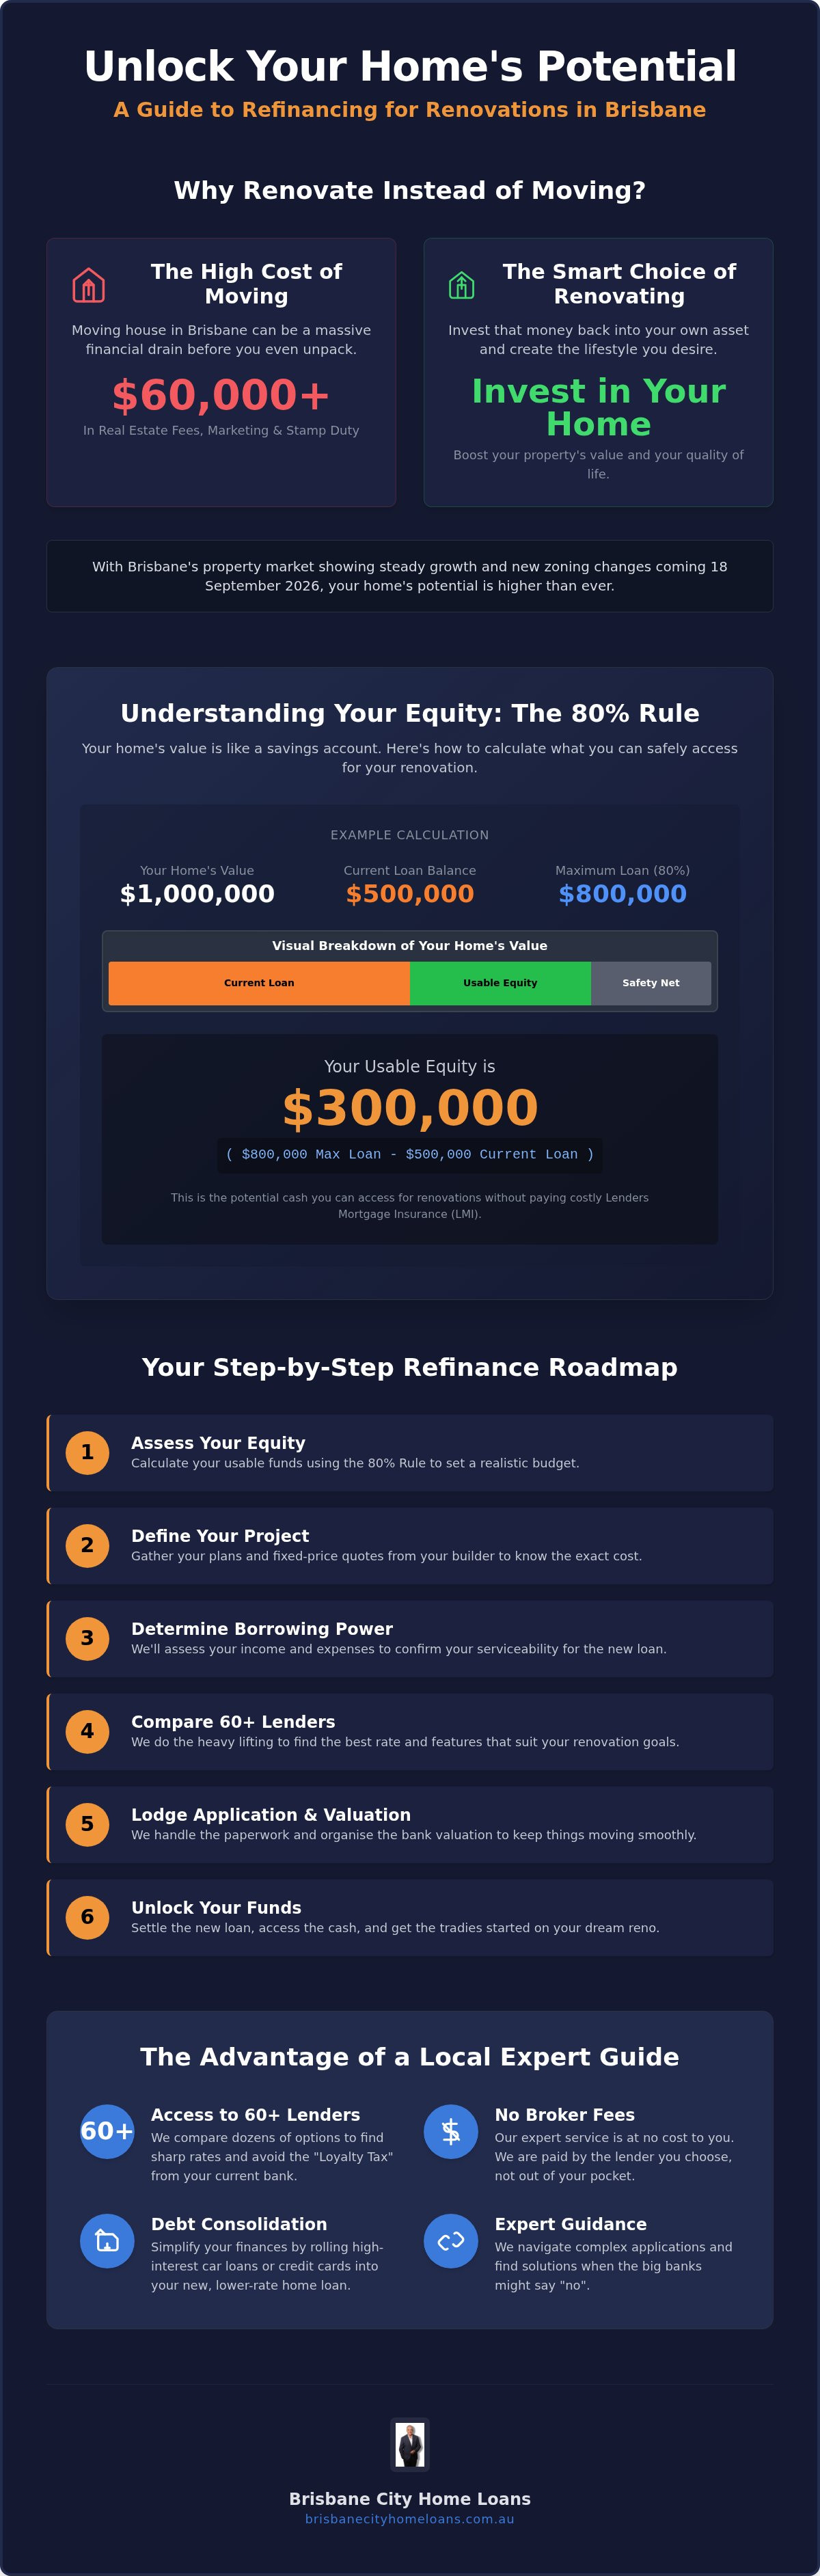
Banks don't let you spend every cent of your home's value because they need a safety net. The 80% Rule is the standard here. This means you can typically borrow up to 80% of what the house is worth today, minus what you still owe. To find your number, simply subtract your current loan from 80% of your home's estimated value. That is your usable equity. It is the actual cash you can grab to pay for that new kitchen or the backyard deck you have been dreaming about.
Calculating Your Borrowing Power
It is not just about the house; banks also look at your "serviceability." This is just a way of asking if you can comfortably afford the new repayments. They will look at your income and your regular spending, from groceries to school fees. Going above the 80% mark triggers Lenders Mortgage Insurance (LMI). This is a fee that protects the bank, not you. It can add thousands to your loan, so most people try to avoid it. Using a home loan refinance calculator brisbane helps you see where you stand before you apply. When refinancing your home loan, having these numbers ready makes the whole process much smoother. Knowing how much you can access is the first step to a successful refinance for renovations Brisbane project.
Valuations: The Make-or-Break Moment
The bank needs to know what your house is actually worth in today's market. Sometimes they use a "desktop valuation" based on recent sales in your street. Other times, a valuer will visit for a full physical inspection. To get the best result, make sure the house is tidy and the garden looks cared for. If a valuation comes back lower than you expected, don't panic. Different lenders use different valuation companies, and some are more conservative than others. If you're feeling a bit stuck on the math, chatting with a local expert can help you find a lender that sees the true value in your home.
Comparing Your Options: Refinance vs. Top-up vs. Construction Loan
Choosing the right way to fund your project is just as vital as picking the right builder. You have a few paths forward, and the best one depends on whether you are just updating a bathroom or completely gutting the place. For many people looking to refinance for renovations Brisbane houses provide the perfect canvas; however, the bank's rules change depending on the scope of the work. You don't want to get halfway through a kitchen rip-out only to realise your loan structure isn't fit for purpose.
A "top-up" is when you stay with your current lender and just increase your existing mortgage. Banks love these because they are easy to process, but they often keep you stuck on a "lazy" interest rate. Refinancing, on the other hand, means moving your entire loan to a new lender. This is usually the smartest move because it allows you to hunt for the lowest possible rate while accessing your equity. Whatever you do, try to avoid using personal loans or credit cards for big renos. The interest rates on those can be double or triple what you would pay on a home loan, which can quickly turn a dream project into a financial nightmare.
Refinancing to Access Cash
If you are doing cosmetic work like painting, floorboards, or a new kitchen, "cashing out" your equity is often the simplest path. This involves refinancing your loan to a higher amount and taking the extra funds as a lump sum. You then have the cash sitting in an offset account ready to pay your tradies. This gives you total control over the budget. Because Andrew compares over 60 lenders, he can find the ones that are most generous with "cash out" limits. He does all the heavy lifting with the paperwork so you can focus on choosing your colour schemes.
When a Construction Loan is Necessary
For the big jobs, a standard refinance might not cut it. If you are planning to add a second storey, move structural walls, or raise a classic Queenslander to build in underneath, banks will usually require a construction loan. Instead of giving you all the money at once, the bank pays your builder in stages as the work is completed. This protects you by ensuring the builder only gets paid for work they have actually done. It's a bit more involved, but it's the safest way to manage a major structural transformation in the 2026 Brisbane market.
The Brisbane Reno Roadmap: Step-by-Step
Ready to start? Breaking the process down into bite-sized pieces makes the whole thing feel much less daunting. When you refinance for renovations Brisbane style, you aren't just dealing with a bank; you are navigating council rules and local tradie schedules too. Here is the path from your current home to your dream one.
- Step 1: Get an "As-Is" Valuation. We need to know exactly what your home is worth today. This sets the baseline for how much equity you can unlock.
- Step 2: Gather Builder Quotes. Get at least two or three detailed quotes. With trade labor costs for tilers and waterproofers at a premium in 2026, you need to know the real numbers before you sign anything.
- Step 3: Check Council Requirements. Most Brisbane renovations only need a Building Approval from a private certifier. However, if you are doing something big, you might need a Development Application (DA).
- Step 4: Andrew Finds the Lender. While you are busy picking out paint colours and tapware, Andrew does the heavy lifting to find a lender that loves your project as much as you do.
Planning for Success in Brisbane
Brisbane has unique "character" overlays, especially in older suburbs like Paddington or Ashgrove. If your home is pre-1946, you need to be careful with what you change. It is also vital to avoid over-capitalising. You don't want to spend $400,000 on a reno if the highest sale in your street is only $100,000 more than your current value. Always include a 10% to 20% "buffer" in your loan. Unexpected things happen once you start pulling off weatherboards, and having that extra cash ready means the work doesn't have to stop. If you aren't sure where to start, organise your free strategy session with Andrew to get your numbers sorted.
The Application and Settlement Process
The paperwork isn't as scary as it sounds. You will generally need your last two payslips, your most recent group certificate, and three months of bank statements showing your living expenses. If you are doing a structural reno, we will also need your signed builder’s contract. Most applications take a few weeks from the first chat to the final approval. On settlement day, your old loan is paid off, your new one starts, and the extra funds for your reno are moved into your account. Brisbane's DA approval rate is high at 95.7%, and the median decision time is around 62 days, so once your finance is ready, you can move forward with confidence.
How Brisbane City Home Loans Makes Renovating Easy
Dealing with banks can feel like a full-time job. Between the hold music and the technical talk, it is enough to make anyone put their reno plans on the back burner. That is why I started Brisbane City Home Loans. When you want to refinance for renovations Brisbane families deserve a process that is as exciting as the project itself. You won't be dealing with a faceless call centre or an automated system. You get me, Andrew, a local who knows the Brisbane market and wants to see your home reach its full potential.
The Andrew/Broker Advantage
Walking into your local bank branch gives you exactly one choice. If they say "no" or offer a mediocre rate, you are stuck. Comparing over 60 lenders changes the game completely. It means we can find the specific lender that is most comfortable with your project, whether you are doing a quick cosmetic update or a major structural overhaul. I take care of all the "heavy lifting" when it comes to the paperwork. This includes tailoring a refinance investment property loan Brisbane investors can use to boost the value of their rentals. My goal is to make the finance side feel effortless so you can focus on the fun parts of the build.
One of the best parts of this journey is that my service does not cost you a cent. The lenders pay me for doing the work they would otherwise have to do themselves. You get expert guidance, a massive range of options, and a personalised plan without any broker fees. I am with you from that first nervous chat right through to the final coat of paint on your new walls. If things get complicated with a valuation or a builder's quote, I am right there in your corner to sort it out.
Ready to Start Your Brisbane Reno?
Booking a chat is the easiest thing you will do all week. There is no pressure, no judgment, and no obligation to move forward. We can meet up and talk through your goals in plain English. For our first meeting, just bring a rough idea of what you want to do and your latest mortgage statement. We will look at your borrowing power and see what is possible in the current 2026 market. My promise to you is simple: I will give you honest advice and clear answers. Let's make that dream renovation a reality without the financial stress.
Turn Your Reno Vision Into a Reality
Your Brisbane home is more than just a place to live; it is a growing asset that can fund the lifestyle you have been dreaming about. By now, you should have a clear picture of how your usable equity works and why the 80% rule is your best friend for staying financially safe. Whether you are planning a simple kitchen refresh or a massive structural lift, choosing to refinance for renovations Brisbane style is about making your property work harder for you without the stress of moving costs.
You don't have to navigate the 60+ lenders or the mountain of paperwork on your own. I am here to do the heavy lifting for you, providing a 100% free service that puts your comfort first. As a local Brisbane expert, I'll help you compare the market to find a deal that actually fits your project and your budget. Ready to see what your home can really do? Book a free, no-obligation chat with Andrew today and let's get those plans moving. I can't wait to hear about your vision for your home.
Frequently Asked Questions
Can I refinance for renovations if I have only owned my home for a year?
Yes, you certainly can, provided there is enough equity in the property. While many people wait longer, a year of strong growth in Brisbane can sometimes build up enough "paper wealth" to fund a smaller project. It really comes down to your initial deposit and how the local market has moved. I can help you look at your current valuation to see if the numbers stack up for a reno loan.
How much equity do I need to refinance for a kitchen renovation in Brisbane?
To avoid extra costs like Lenders Mortgage Insurance, you generally need to keep 20% of your home's value untouched. For a mid-range kitchen reno in 2026, which often costs between $20,000 and $80,000, you would need that amount available as "usable equity." This is the gap between your current loan and 80% of your home's total value. We can do a quick calculation together to see what your budget looks like.
What happens if my home valuation is lower than I expected?
If a valuation comes back lower than you hoped, don't lose heart. Different banks use different valuation firms, and some are much more conservative than others. Because I compare over 60 lenders, we can often simply try a different one that might see more value in your property. We can also look at "as-complete" valuations, which take your future renovation plans into account to help boost your borrowing power and get the deal done.
Do I need council approval before I can get my renovation loan approved?
Not always. For cosmetic updates like new flooring or a kitchen swap, you usually don't need council approval to get your finance sorted. However, for structural changes like adding a bedroom or raising a Queenslander, the bank will often require a Building Approval or Development Application from the Brisbane City Council before they release the final funds. We will check your specific plans to see which rules apply to your project before we apply.
Is it better to top up my current mortgage or refinance to a new bank for a reno?
While a top-up feels like the path of least resistance, it often means you miss out on better deals. Refinancing to a new lender is a great way to escape the "loyalty tax" and grab a lower interest rate. When you refinance for renovations Brisbane lenders are often very competitive to win your business. I'll compare your current bank's top-up offer against 60 other options to make sure you aren't overpaying for your money.
How long does it typically take to refinance for renovations in Brisbane?
Most people find the process takes between two to four weeks from our first chat to having the cash ready. This includes getting your home valued and the bank doing their final checks. Brisbane City Council DA approvals can take around 62 days if you need them, but the finance side is usually much faster. I'll handle the paperwork and follow up with the lenders to keep things moving as quickly as possible for you.
What are the costs involved in refinancing my home loan?
You might see a few small costs like a discharge fee from your old bank and a government registration fee for the new mortgage. These are usually around a few hundred dollars. The good news is that my service is completely free for you, as the lenders pay me a commission. Often, the savings you get from a lower interest rate or a lender "cashback" offer will cover these small entry costs very quickly.
Can I refinance for a renovation if I am self-employed in Brisbane?
Absolutely. Being self-employed shouldn't stop you from building your dream home. While big banks can sometimes be a bit fussy with paperwork for business owners, I work with plenty of lenders who have a common-sense approach. You might just need to show your latest tax returns or a letter from your accountant. I'll help you organise your documents so the bank sees the full picture of your financial strength and says yes.


