
Your Brisbane home might be doing more work than you realise. While you're busy living life, your property has likely been building a hidden savings account in the background. Learning how to access home equity brisbane style isn't about taking on scary debt. It's about using the growth you've already earned to create new opportunities for your family.
It's completely normal to feel a bit stuck when banks start throwing around terms like LVR or usable equity. You might wonder if your suburb's growth is actually enough to make a move, or worry that you'll end up over-leveraged. I get it. The financial world often feels like it's designed to be confusing; however, it doesn't have to stay that way. You deserve to feel comfortable and in control of your own mortgage.
This guide will show you exactly how to unlock your home's value and turn that growth into real financial opportunities. We'll look at the 2026 Brisbane market, where median home values are sitting around $1.1 million, and break down how you can use those figures to your advantage. From funding a renovation to securing a lower interest rate through refinancing, you'll get a clear, jargon-free plan to move forward with confidence.
Key Takeaways
- Identify your equity by calculating the difference between your home's current 2026 market value and your remaining loan balance.
- Discover the practical steps for how to access home equity brisbane property owners take to either top up an existing loan or refinance for better terms.
- Learn how to use your property growth to fund a local renovation or act as a deposit for an investment property in South-East Queensland.
- Understand the risks of over-leveraging and why maintaining a healthy buffer is essential for your long-term financial comfort.
- See why comparing over 60 different lenders with a local guide helps you skip the jargon and find a deal that actually fits your life.
What Exactly is Home Equity in the Brisbane Context?
Home equity is the portion of your property you truly own. It's the difference between what your home is worth on the 2026 market and the amount you still owe the bank. If you've ever wondered what is home equity, think of it as your property's net worth. It's a hidden financial engine that grows as you pay off your loan and as Brisbane property prices climb.
Brisbane isn't just one big market; it's a collection of unique pockets. In 2026, we're seeing that a home in Paddington might have a very different equity story compared to a property in Chermside or Logan. This is because local growth isn't always even. Understanding these suburb specific shifts is the secret to knowing how to access home equity brisbane residents can use for their next big goal.
How Brisbane Suburb Growth Impacts Your Equity
The value of your home depends heavily on what's happening just outside your front door. Major infrastructure projects tied to the 2032 prep are already shifting values in certain areas. A professional valuer doesn't just look at your kitchen or backyard; they look at the neighbourhood's demand and recent sales. This is why your equity might have jumped even if you haven't picked up a paintbrush in years. This local insight is the first step in learning how to access home equity brisbane homeowners often miss.
Calculating Your Usable Equity
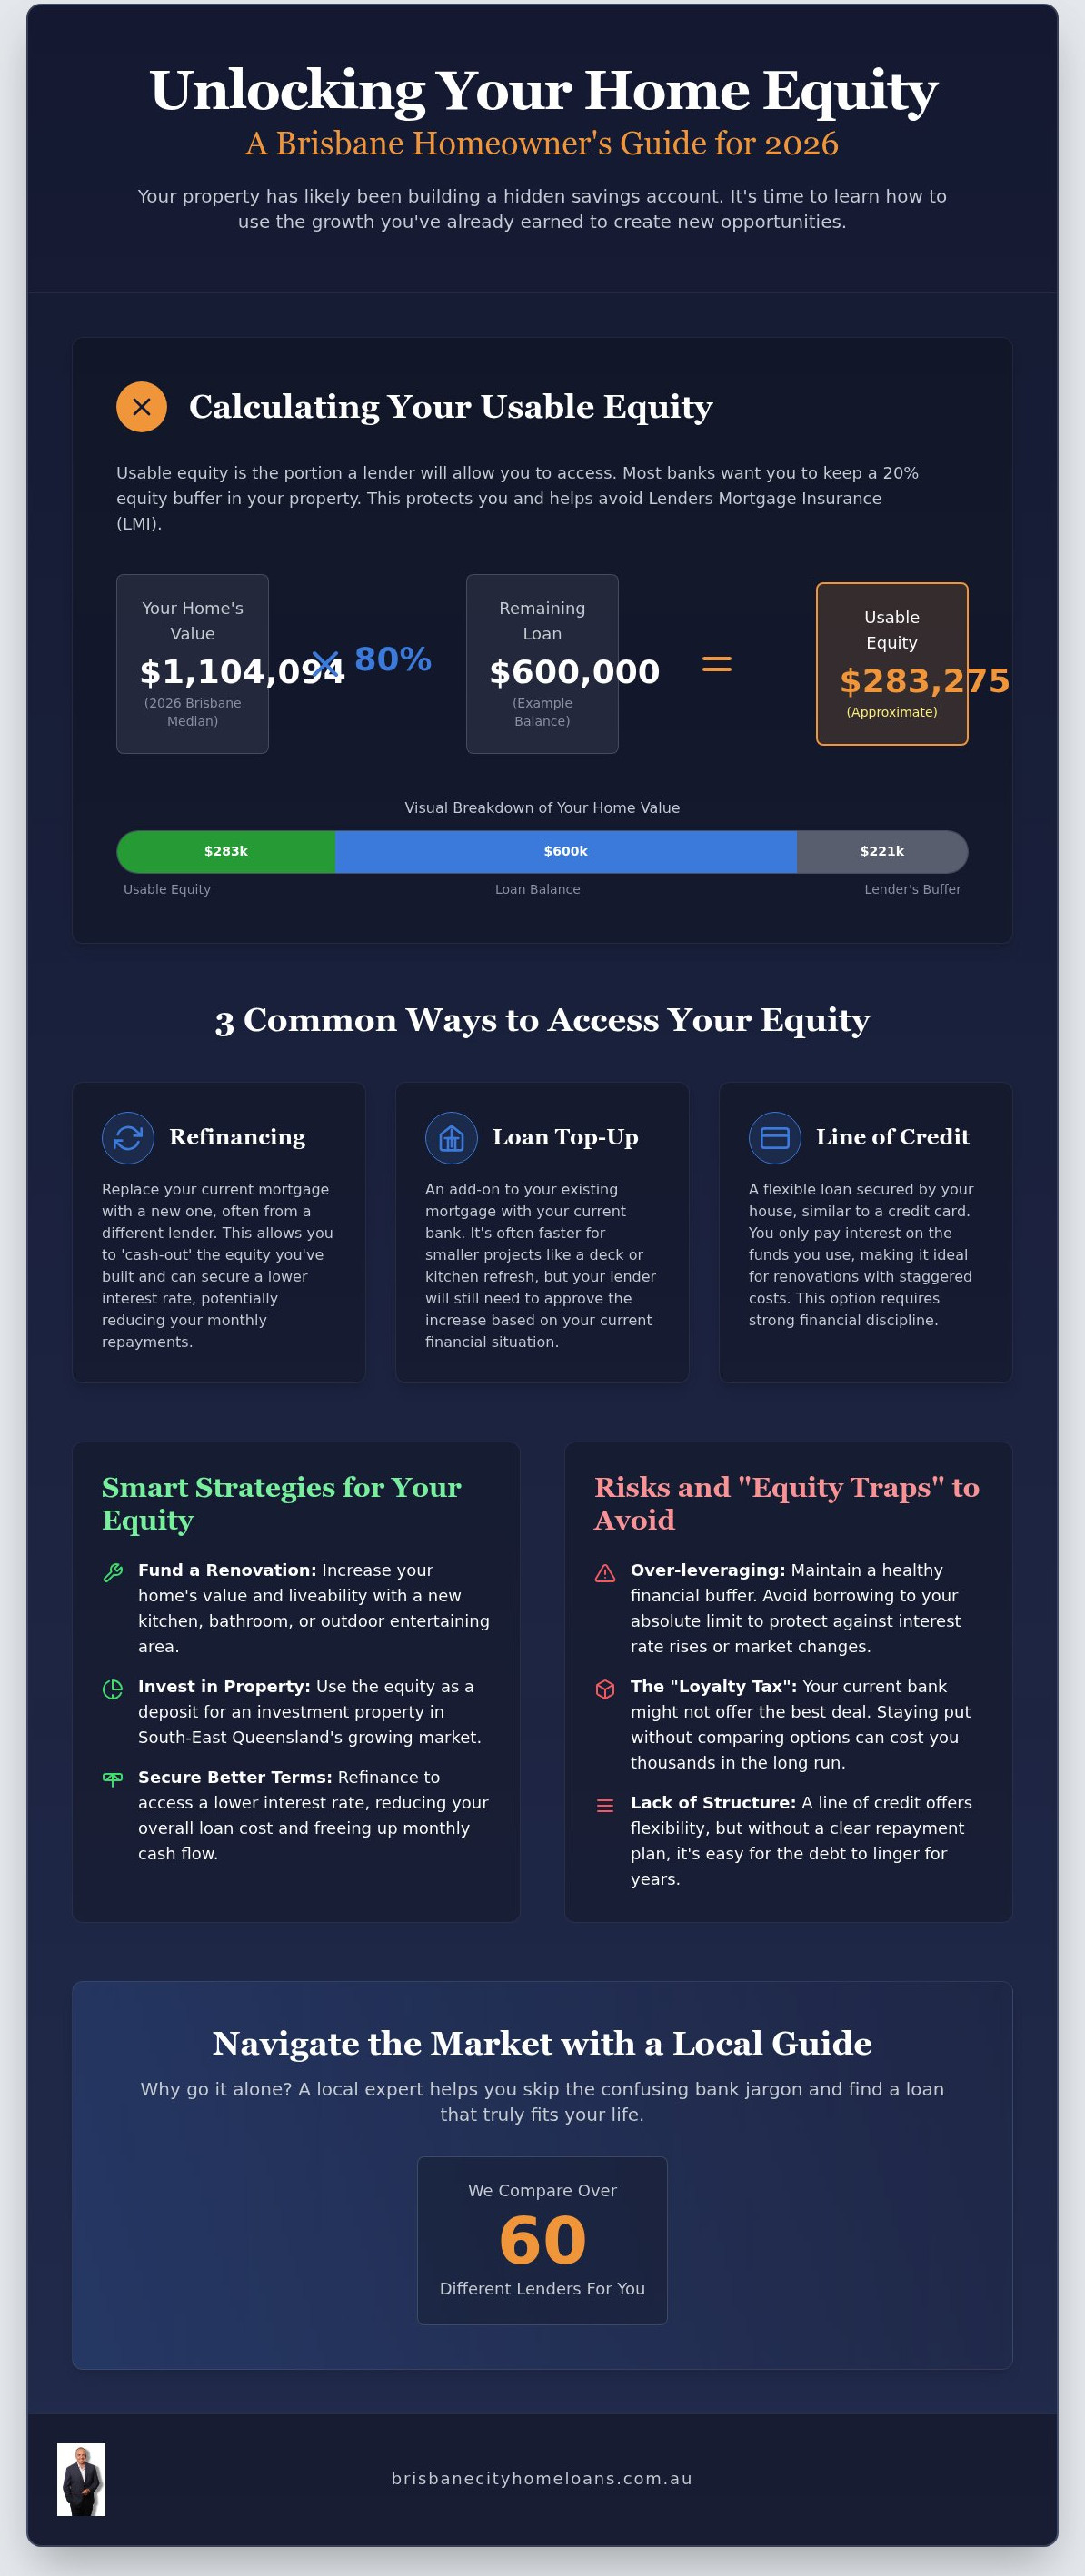
There's a big difference between "total equity" and "usable equity." Total equity is the whole gap between your value and your debt. Usable equity is the part the bank will actually let you touch. Most lenders want you to keep a 20% buffer in the property. This protects you if the market dips and helps you avoid the extra cost of Lenders Mortgage Insurance (LMI).
The math is actually quite simple. You take 80% of your home's current value and subtract your remaining loan balance. Let's look at a quick example using the 2026 median Brisbane home value of $1,104,094. If you owe $600,000 on your mortgage, the bank looks at 80% of that $1.1 million figure, which is roughly $883,275. Subtract your $600,000 loan, and you have approximately $283,275 in usable equity. That's the amount you could potentially use to fund a renovation or a deposit on an investment property.
The 3 Most Common Ways to Access Your Equity
Accessing your equity shouldn't feel like a chore. It's about finding the right tool for your specific goal. You generally have three paths to choose from. Each has its own perks, but remember, your current bank might not be the best place to start. Many homeowners pay a "loyalty tax" by staying with an old loan when a better deal is waiting elsewhere. Exploring how to access home equity brisbane property growth has provided is often more successful when you look at the wider market.
Refinancing for a Fresh Start
Refinancing is essentially replacing your current mortgage with a new one, often with a different lender. It's a powerful way to look at how to access home equity brisbane property owners have built up over the years. During this process, you can do what's called a "cash-out." This means you borrow more than your current debt and take the difference as cash to use for your next project. If you're looking to Refinance Your Investment Property Loan in Brisbane, this can be a smart move to free up funds for another purchase while potentially scoring a lower interest rate.
The Loan Top-Up: Pros and Cons
A loan top-up is like an add-on to your existing mortgage. You stay with your current bank but increase the limit of your loan. It's often the fastest way to get cash for smaller things, like a new deck or a kitchen refresh. However, banks can still say "no" even if you have plenty of equity. They'll look at your income and expenses again to make sure you can handle the extra repayments. It's always worth checking your current loan features first to see if a top-up is even an option. You don't want to get halfway through a plan only to find your current lender has strict limits on add-ons.
Line of Credit: Flexibility vs. Discipline
Think of a line of credit like a giant credit card secured by your house. You only pay interest on the money you actually spend. It's great for renovations where costs pop up at different times. The catch? It requires a lot of discipline. Because you aren't always forced to pay back the principal every month, it's easy for the debt to sit there forever. This is why I often suggest fixed-term loans for families. They provide a clear end date and more structure. If you're unsure which path is right for you, Andrew can help you compare your options without any pressure or complicated talk.
Smart Strategies for Using Your Equity in QLD
Once you understand how to access home equity brisbane property growth has generated for you, the fun part begins. How do you make that value work for your future? It's not just about having extra cash in the bank; it's about making moves that improve your lifestyle or build your wealth. Whether you want to grow your property portfolio or finally fix up that old kitchen, your home is often the key to making it happen without the stress of saving for years.
Building a Property Portfolio
Many Brisbane locals use their equity to buy a second home or an investment property in South-East Queensland. The best part? You can often bypass the need for a massive cash deposit. By using your existing home as security, you can cover the deposit and costs for the new place. This is a popular strategy in 2026 as people look to secure their spot in our growing city.
While this is exciting, I always watch out for the "cross-collateralisation" trap. This is a fancy way of saying the bank ties all your properties together in one big loan. It sounds easy, but it can limit your choices later if you want to sell or switch banks. I usually prefer to keep your loans separate so you stay in the driver's seat. If you're looking at helping your kids get into the market, you might also want to check out my First Home Buyers QLD guide for 2026.
Renovating for Profit or Comfort
Brisbane is famous for its beautiful "Queenslanders" and post-war cottages. These homes are perfect candidates for equity-funded renovations. Adding a deck, lifting the house, or modernising the bathroom can add immediate value to your property. If you're planning a major build, you'll likely need a specific Construction Loan Brisbane. This type of loan is designed for the unique stages of a building project.
Just be careful not to "over-capitalise." This happens when you spend more on the renovation than what it actually adds to the home's value. It's a common worry for many of my clients. I can help you look at recent sales in your suburb to make sure your project makes financial sense for your specific street and suburb profile.
Beyond property, you can also use equity for:
- Consolidating high-interest debt: Moving car loans or credit cards into your mortgage can significantly lower your monthly outgoings.
- Investing in other assets: Some people use their equity to buy shares or diversify their wealth outside of property.
- Providing a safety net: Having access to funds can offer huge peace of mind for your family's future.
Risks and "Equity Traps" to Watch Out For
Let's have a quick reality check. While it's exciting to see your property value climb, equity isn't exactly "free money." When you look at how to access home equity brisbane property growth has provided, you're essentially asking the bank for a bigger loan. This means your total debt goes up, and your monthly repayments will follow. It's a powerful tool for building wealth, but it needs to be handled with a bit of care to keep your family's finances comfortable.
One common trap is relying too heavily on automated online estimates. You might see a high figure on a real estate website and think you're sitting on a goldmine. However, a local valuer in 2026 might see things differently. They look at specific sales in your street and the actual condition of your home. If the market takes a slight dip, your "usable" equity can shrink faster than you'd expect. Keeping a healthy buffer ensures you aren't left over-leveraged if the Brisbane market cools down after its recent peak.
Understanding LVR and LMI
In the world of home loans, 80% is the magic number. This is your Loan to Value Ratio (LVR). If you borrow more than 80% of what your home is worth, banks usually charge you Lenders Mortgage Insurance (LMI). This is a one-off fee that protects the bank, not you. For most Brisbane families, staying under that 80% mark is the sweet spot to avoid these extra costs.
Sometimes, paying LMI can actually be a smart move if it helps you secure a great investment property before prices rise further. It's all about weighing up the cost versus the potential gain. If you're trying to help a family member get into the market without using your own cash, a Guarantor Home Loan Brisbane might be a better alternative to explore. It allows you to help out without necessarily increasing your own debt as much.
The Impact of Rising Interest Rates
More debt means more sensitivity to interest rate changes. If the RBA decides to hike rates, that larger loan balance will feel the pinch more than your old one did. I always suggest building a "stress buffer" into your family budget. This means making sure you can still afford the lifestyle you love even if rates go up by a percent or two.
I take a very no-nonsense approach to this. We'll sit down and look at your actual numbers to see how a larger loan fits into your real life. There's no judgment here; just clear facts to give you peace of mind. If you want to see what's possible for your situation, Andrew can help you stress-test your plan before you sign anything.
How Andrew at Brisbane City Home Loans Makes it Easy
Walking into your local bank branch can often feel like being a small fish in a very large, corporate pond. They only have their own products to show you, which means you're limited to whatever they have on the shelf. Andrew does things differently. He compares over 60 lenders to find the one that actually fits your life and your goals. This is the simplest way to figure out how to access home equity brisbane property growth has gifted you without feeling like just another number in a system.
The "Andrew Difference" is all about keeping things human. There is no bank jargon, no judgment about your financial past, and absolutely no pressure. It's just honest help from a local who knows the South-East QLD market inside out. Best of all, there is no cost to you as the borrower. Because the lenders pay a commission, you get expert guidance and a personalised roadmap for free. Andrew handles the messy paperwork and the back-and-forth with the banks, so you can focus on the exciting part: planning your future.
The Free Consultation Process
Everything starts with a simple, 15-minute chat. This isn't a high-stakes interview; it's just a casual conversation to see what's possible for you. You might be surprised by how little you actually need to get started. While you will eventually need to organise some basic documents like pay slips or bank statements, Andrew will tell you exactly what's required and when. He takes over the heavy lifting from day one, ensuring you know exactly how to access home equity brisbane lenders are currently offering for your specific suburb and property type.
Ongoing Support for Brisbane Families
Our commitment to you doesn't end when the loan settles. The 2026 property market moves fast, and Andrew stays in your corner to make sure your loan remains the right fit as things change. He'll check in regularly to see if there's a better rate available or if your equity has grown enough for your next move. It's about building a long-term partnership with a local guide who truly cares about the Brisbane community. You aren't just getting a loan; you're getting a dedicated advocate for your financial well-being.
Ready to see how much equity you have? Get in touch with Andrew today.
Ready to Turn Your Property Growth into Your Next Opportunity?
Your home is more than just a place to live; it's a powerful financial asset that can open doors for your family. We've covered the essentials of usable equity and how to stay on the right side of the 80% rule to avoid extra costs. Knowing how to access home equity brisbane residents have built up during this property cycle gives you the confidence to fund a renovation or start an investment journey without the stress of saving for years.
You don't need to be a finance expert to make these moves. With access to over 60 Australian lenders and a deep knowledge of the local market since 2022, Andrew is here to do the heavy lifting for you. It's a 100% free service for borrowers, designed to replace bank jargon with clear, helpful advice that puts you first. There's no judgment and no pressure; just a straightforward path to your goals.
Book a free, no-obligation equity chat with Andrew today to find out exactly what your home can do for you. You've worked hard to build your property's value; now it's time to let that value work for you.
Frequently Asked Questions
How much equity can I actually take out of my home?
Generally, you can access up to 80% of your home's current value minus your existing debt. This keeps you in the "sweet spot" to avoid the extra cost of Lenders Mortgage Insurance. If your Brisbane home is valued at $1.1 million, the bank looks at 80% of that figure, which is $880,000. If you owe $500,000, your usable equity is $380,000. It's about finding a balance that keeps your repayments comfortable.
Do I need a new valuation to access my home equity?
Yes, lenders will almost always require a fresh valuation to confirm your property's 2026 market price. Since Brisbane values have shifted recently, an old estimate won't be enough for a formal application. The bank will send out a professional valuer to inspect your home and compare it to recent sales in your specific suburb. This ensures they are lending against an accurate figure, which protects you from over-leveraging your position.
Can I access equity if I am self-employed in Brisbane?
Absolutely, being self-employed doesn't lock you out of your property's growth. While the paperwork might look a bit different compared to a standard PAYG employee, many of the 60+ lenders Andrew works with specialise in loans for business owners. You'll generally need your recent tax returns or a BAS to show your income. We'll work together to find a lender that understands your business structure and values your hard work without the stress.
Is it better to use a line of credit or a loan top-up?
It depends on your specific project. A loan top-up is often cheaper and simpler for a one-off cost, such as a deposit for another home. A line of credit offers more flexibility for ongoing costs like a long-term renovation, but it requires much more discipline to pay back. Andrew usually finds that a standard loan top-up or refinancing is the most predictable and cost-effective way for most Brisbane families to manage their debt.
How long does the process of accessing equity usually take?
You can usually expect the process to take between two to four weeks from your first chat to having the funds ready. This includes the time for the bank's valuation and the formal approval. If you are refinancing to a new lender, it might take slightly longer due to the discharge process with your old bank. Andrew handles the heavy lifting and follow-ups to keep things moving as quickly as possible for you.
What are the costs involved in refinancing to access equity?
While Andrew’s service is 100% free for you, there are some standard third-party costs to keep in mind. These typically include a discharge fee from your current lender and government registration fees for the new mortgage. Some lenders might also charge an application or valuation fee, although many offer deals that waive these. We will look at the total cost together to ensure the move makes clear financial sense for your specific situation.
Can I use equity to buy an investment property in another state?
Yes, your Brisbane equity can certainly be used as a deposit for a property anywhere in Australia. Many locals use the growth in their primary home to snap up an investment in other capital cities to diversify their wealth. When looking at how to access home equity brisbane property owners often find that their local growth provides enough "cash" to cover the entry costs and stamp duty of a more affordable interstate market.
Will accessing my equity increase my monthly mortgage repayments?
Yes, it generally will because you are increasing the total amount you owe the bank. It's important to factor this into your family budget before you commit to the change. However, if we refinance your loan to a lower interest rate at the same time, the increase might be smaller than you expect. Andrew will help you run the numbers so you know exactly how the new repayments will feel in your day-to-day life.


